20 Oct Your Tax Bracket: What Retirees Should Know
Your Tax Bracket May Not Tell the Whole Story: What Retirees Should Know
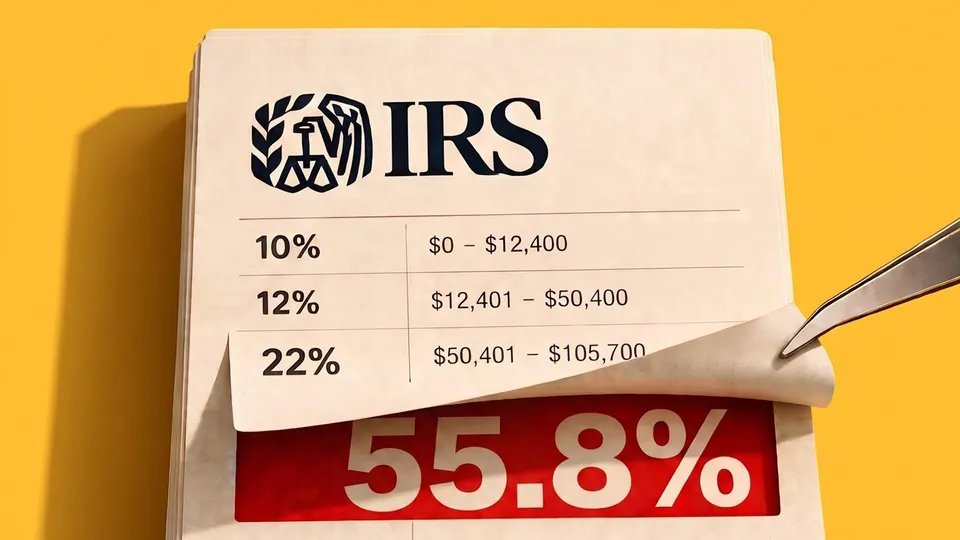
What tax bracket are you in? If you answered 22% or 24%, you might be surprised to learn that your next financial decision could have a much greater tax impact.
That’s because your federal income tax bracket doesn’t always reflect the full cost of earning additional income, taking an IRA withdrawal, or converting retirement savings to a Roth IRA.
For retirees, understanding your marginal tax rate in retirement can be an important part of making informed financial decisions.
At Nova Wealth Management, we believe tax planning should consider more than what you owe this year. It should also evaluate how today’s decisions may affect your retirement income and future financial flexibility.
What Is Your Marginal Tax Rate?
Your marginal tax rate is the rate at which your next dollar of taxable income is taxed. It’s different from your effective tax rate, which represents the average federal income tax rate paid across your taxable income.
For example, someone in the 22% federal income tax bracket doesn’t necessarily pay 22% on all their income. Different portions of taxable income are subject to different rates.
But there’s another consideration: The actual financial impact of additional income may extend beyond your ordinary income tax bracket.
An additional IRA withdrawal or Roth conversion could potentially affect:
- The taxation of Social Security benefits
- Eligibility for certain tax deductions or credits
- Exposure to additional taxes on investment income
- Future Medicare premiums
These interactions can make the overall cost of a financial decision higher than the tax bracket alone might suggest.
Why Retirement Income Can Create Unexpected Tax Consequences
Retirement income often comes from several sources, and those sources aren’t necessarily taxed the same way.
Traditional IRA and 401(k) withdrawals are generally subject to ordinary income tax, while qualified Roth IRA withdrawals are generally tax-free.
Long-term capital gains and qualified dividends may receive different federal tax treatment. Social Security benefits may also become partially taxable depending on your combined income.
When these income sources overlap, an additional withdrawal can sometimes trigger consequences beyond the income tax owed on the withdrawal itself.
For example, a retiree considering an additional $10,000 IRA withdrawal might initially calculate the federal tax using their current income tax bracket.
However, that withdrawal could also increase the taxable portion of Social Security benefits or affect income-based thresholds used for other financial calculations.
The important question isn’t simply, “What tax bracket am I in?” It’s, “What happens to my overall financial picture if I make this decision?”
The Difference Between Paying Taxes and Planning for Taxes
Many retirees focus on reducing their current tax bill. While that can be worthwhile, the lowest tax bill today doesn’t always produce the most favorable long-term outcome.
Consider someone deciding whether to withdraw additional money from a traditional IRA or complete a partial Roth conversion.
The decision may create additional taxable income today, but it could also change the amount of pretax retirement savings available for future withdrawals.
Evaluating that trade-off requires looking beyond one year’s tax return.
That’s why thoughtful retirement planning considers how income, investments, Social Security, and taxes interact over time.
A financial decision should be evaluated based on its potential impact on your overall retirement plan—not just the tax rate printed on a chart.
How Roth Conversions Can Affect Your True Tax Rate
Roth conversions can be an important retirement tax-planning consideration, but understanding their full financial impact is essential.
When you convert money from a traditional IRA to a Roth IRA, the taxable portion of that conversion generally increases your ordinary income for the year.
That additional income could move you into a higher tax bracket, affect other tax calculations, or increase future Medicare premiums.
However, paying additional taxes today may sometimes provide greater flexibility later, since qualified Roth IRA withdrawals are generally tax-free.
The question isn’t whether Roth conversions are good or bad. It’s whether a conversion makes sense for your individual financial circumstances.
Medicare IRMAA: A Retirement Tax Planning Consideration
One commonly overlooked consequence of additional retirement income is its potential effect on Medicare premiums.
Medicare uses income-related monthly adjustment amounts, known as IRMAA, to determine whether certain beneficiaries pay higher premiums for Medicare Parts B and D.
These adjustments generally use income information from two years earlier.
For example, additional taxable income from a Roth conversion or IRA withdrawal in 2026 could potentially affect Medicare premiums in 2028.
Because IRMAA operates using income thresholds, even a relatively small increase in income can sometimes trigger a higher premium tier.
That’s why evaluating your marginal tax rate in retirement should include more than federal income taxes alone.
How to Evaluate Retirement Tax Decisions
Before making a significant financial decision, consider how it could affect your complete retirement income picture.
- Review your income sources: Understand how Social Security, retirement accounts, pensions, and investments interact.
- Evaluate additional withdrawals: Consider the tax consequences before taking more money than required from retirement accounts.
- Consider Medicare thresholds: Review whether additional income could affect future premiums.
- Coordinate tax planning: Work with your financial advisor and tax professional to evaluate potential outcomes.
At Nova Wealth Management, we believe tax-aware retirement planning should support your broader financial goals.
For individuals and families in Bonita Springs, Naples, Estero, Fort Myers, and throughout Southwest Florida, our team helps evaluate how retirement income decisions, investment strategies, and tax considerations fit together.
Understanding the potential consequences before making a financial decision can help you evaluate your options more effectively.
Frequently Asked Questions
Can my actual tax rate be higher than my federal tax bracket?
Yes. Additional income may affect deductions, credits, Social Security taxation, or other tax calculations. These interactions can make the overall financial impact greater than your stated federal income tax bracket.
Can a Roth conversion increase Medicare premiums?
Yes. A taxable Roth conversion may increase your modified adjusted gross income and potentially trigger higher Medicare Part B and Part D premiums, generally two years later.
Should retirees always avoid moving into a higher tax bracket?
Not necessarily. Paying additional taxes today may sometimes support longer-term retirement goals. The decision should be evaluated based on your financial circumstances and projected future tax exposure.
Make Tax Planning Part of Your Retirement Strategy
Your tax bracket tells only part of the story. Understanding how financial decisions affect your retirement income, investments, and future taxes can provide a more complete picture.
If you’re considering a Roth conversion, additional IRA withdrawal, or other retirement income decision, Nova Wealth Management can help you evaluate how those choices fit into your financial plan.
Ready to review your retirement income strategy? Schedule a meeting with Nova Wealth Management.
Source: Forbes, William Baldwin, Oct. 19, 2026. Licensed through AdvisorStream.
Disclosure: This material is provided for general educational and informational purposes only and does not constitute individualized investment, tax, or legal advice. Tax laws and Medicare rules are subject to change. Nova Wealth Management, Inc. is a Registered Investment Advisor. Individuals should consult qualified tax and financial professionals regarding their specific circumstances.


Sorry, the comment form is closed at this time.