06 Mar Red Flags to Watch for in Federal Retirement Planning
Red Flags to Watch for in Federal Retirement Planning
Federal retirement planning is unique. With programs such as FERS, CSRS (for legacy employees), the Thrift Savings Plan (TSP), and federal survivor benefits, planning decisions can be more complex than traditional retirement structures.
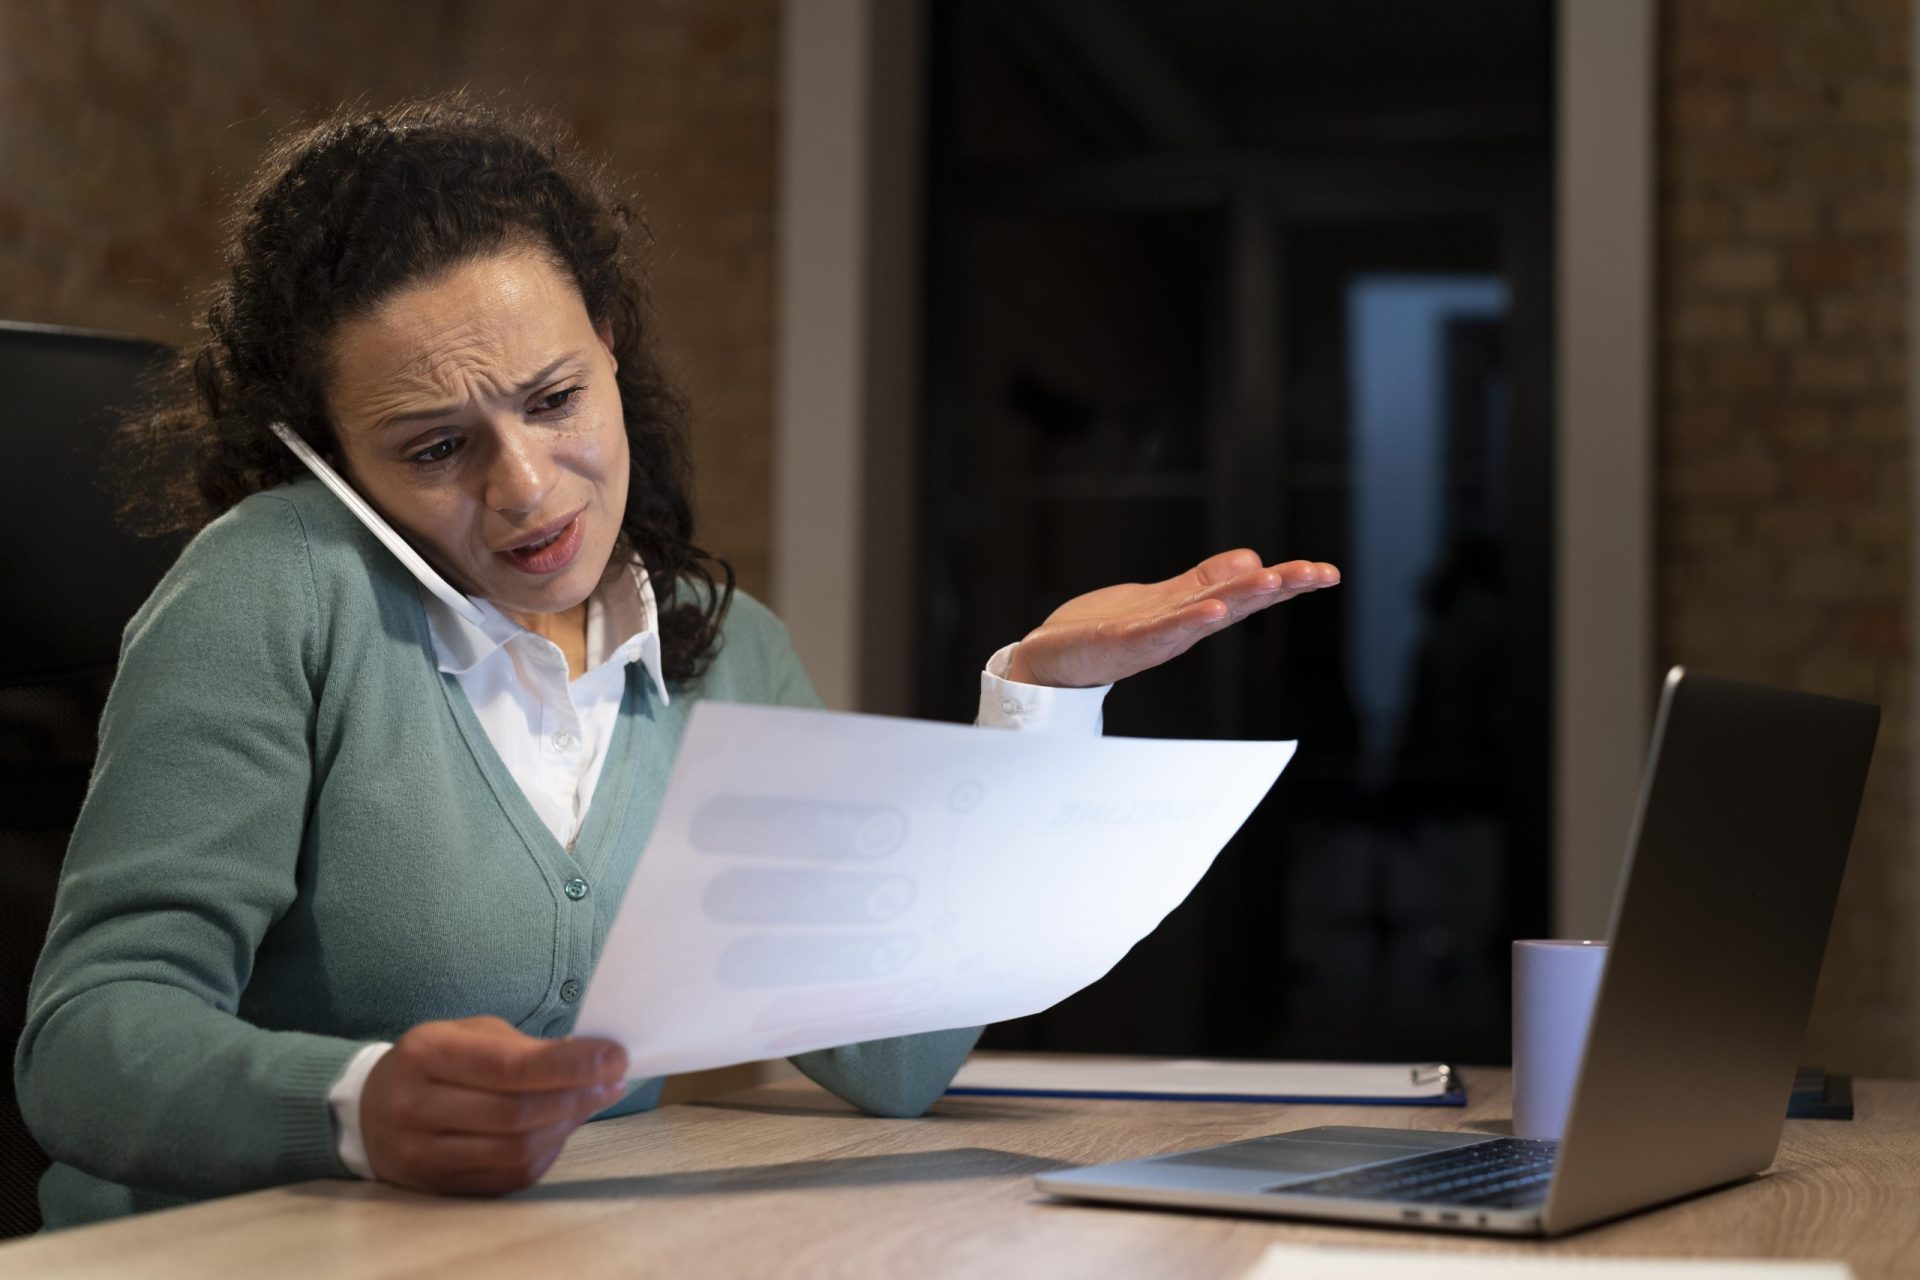
Because of that complexity, it is especially important for federal employees and retirees to recognize potential red flags when evaluating advice or building a retirement strategy.
At Nova Wealth Management, based in Bonita Springs, Florida, we work with federal employees and retirees throughout Naples, Marco Island, Estero, Fort Myers, and surrounding Southwest Florida communities to help ensure retirement decisions are coordinated and informed.
Below are common red flags to watch for in federal retirement planning.
1. Oversimplifying FERS or CSRS Benefits
Federal retirement systems include multiple components:
-
Pension benefits
-
Social Security (for FERS employees)
-
Thrift Savings Plan (TSP) accounts
-
Survivor benefit options
If someone presents federal retirement planning as “simple” without reviewing each component carefully, that may be a warning sign. Federal benefits require coordination and careful evaluation.
→ Learn more:
Federal Retirement Planning
2. Ignoring TSP Withdrawal Strategy
The Thrift Savings Plan is often a primary retirement asset for federal employees.
Red flags include:
-
Recommending changes without reviewing fees and options
-
Ignoring tax implications of withdrawals
-
Failing to coordinate TSP withdrawals with pension income
-
Overlooking Required Minimum Distribution (RMD) rules
TSP decisions should be evaluated in the context of overall retirement income.
3. No Discussion of Tax Implications
Federal retirement income can include:
-
Pension income
-
Social Security
-
TSP withdrawals
-
Other retirement account distributions
If tax planning is not part of the discussion, that is a potential concern.
Federal retirees may face:
-
Income stacking issues
-
IRMAA (Medicare premium adjustments)
-
Required Minimum Distributions
Tax coordination is an important component of comprehensive planning.
→ Related service:
Retirement Tax Planning
4. Pressure to Make Immediate Decisions
Federal retirement decisions often involve:
-
Pension election timing
-
Survivor benefit elections
-
TSP rollover considerations
-
Retirement date timing
High-pressure tactics or “limited-time” framing can be a warning sign. Federal retirement planning should allow time for thoughtful review.
5. Lack of Survivor Benefit Clarity
Survivor benefit elections can significantly affect:
-
Pension income
-
Spousal benefits
-
Long-term financial stability
If survivor benefit options are not clearly explained — including trade-offs — that may indicate incomplete planning.
6. No Integration with Healthcare Planning
Federal retirees must consider:
-
FEHB coverage
-
Medicare coordination
-
Long-term care considerations
If healthcare costs and Medicare timing are not part of the conversation, planning may be incomplete.
→ Learn more:
Health Care Retirement Planning
7. Treating Federal Retirement Like a Standard Corporate Plan
Federal retirement systems are different from traditional 401(k)-only retirement structures.
Red flags may include:
-
Applying generic advice
-
Ignoring pension dynamics
-
Overlooking federal-specific rules
Federal retirement planning should reflect federal realities.
8. No Discussion of Income Sustainability
Federal retirees often have a pension foundation, but sustainability still matters.
Planning should address:
-
Inflation considerations
-
Withdrawal sequencing
-
Longevity planning
-
Investment allocation
A pension alone does not eliminate the need for thoughtful income coordination.
→ Related:
Retirement Income Planning
9. Overemphasis on Investment Returns
Federal retirement planning is not solely about investment performance.
If conversations focus primarily on:
-
“Beating the market”
-
High return projections
-
Short-term performance
…without discussing coordination, taxes, and income, planning may be incomplete.
All investing involves risk, and future outcomes are uncertain.
10. Lack of Ongoing Review
Federal retirement planning is not a one-time decision.
Regular reviews should address:
-
Changes in tax law
-
Medicare adjustments
-
Income needs
-
Investment performance
-
Life transitions
Ongoing oversight supports long-term alignment.
TL;DR — Federal Retirement Planning Red Flags
-
Oversimplifying FERS or CSRS
-
Ignoring TSP coordination
-
Skipping tax planning
-
Using high-pressure tactics
-
Failing to explain survivor benefits
-
Overlooking healthcare planning
-
Applying generic retirement advice
-
Focusing only on returns
-
Not reviewing plans regularly
Federal retirement planning requires coordination, clarity, and thoughtful evaluation of all benefit components.
Next Steps
If you are a federal employee or retiree and would like to review your retirement strategy, our team is here to help.
👉 Contact Us
📞 Phone: (239) 444-1794 (Florida) or (214) 764-9137 (Dallas)
Disclosure: This content is provided for general educational purposes only and does not constitute personalized financial, tax, or legal advice. All investing involves risk, including the potential loss of principal.


No Comments