26 Oct Emotional Investing Decisions: The Hidden Cost of Fear
The Hidden Cost of Fear: How Market Anxiety Can Affect Your Retirement
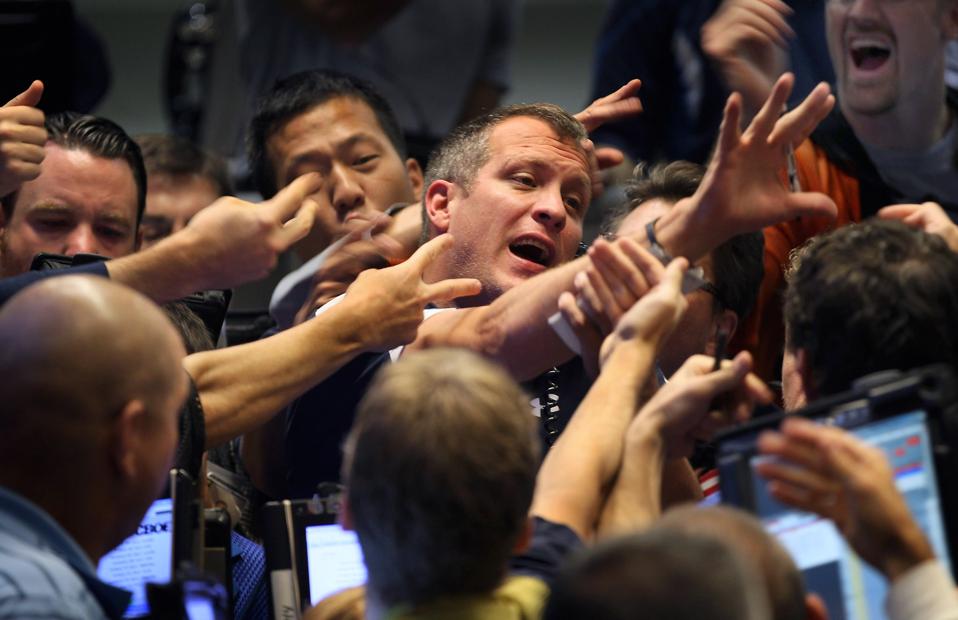
When the stock market drops, what is your first reaction?
Do you immediately check your investment accounts? Wonder how much money you’ve lost? Or start questioning whether you should sell before things get worse?
These reactions are understandable, especially when your retirement savings are involved.
But here’s something worth considering: The market itself isn’t always the greatest threat to your financial plan. Sometimes, it’s how you react to it.
Fear is a natural human response to uncertainty. However, when fear begins influencing financial choices, emotional investing decisions can create consequences that extend well beyond a temporary market decline.
At Nova Wealth Management, we believe understanding the emotional side of investing is an important part of building a retirement strategy that reflects your financial goals, income needs, and tolerance for risk.
Why Market Volatility Triggers Emotional Reactions
Watching your investments decline in value can be unsettling. For retirees and those approaching retirement, those feelings may be even stronger because the money invested represents years of saving and planning.
In an October 2026 Forbes article, psychiatrist Mena Mirhom, M.D., explored how the brain’s emotional response to perceived threats can occur faster than rational decision-making.
When markets become volatile, that immediate emotional response may encourage investors to act quickly, even when taking time to evaluate their options would be more appropriate.
For example, an investor who sees their portfolio decline might feel compelled to sell investments to prevent further losses.
While reducing investment risk can sometimes be appropriate, making significant portfolio changes primarily because of fear may create unintended consequences.
Market volatility and investment risk are not always the same thing. A temporary decline in account value doesn’t necessarily mean an investment strategy is no longer appropriate.
How Fear Can Lead to Costly Investment Decisions
One of the challenges of emotional investing is that decisions made during stressful periods can affect future financial outcomes.
Consider an investor who sells a substantial portion of their portfolio after a market decline.
Initially, moving to cash may provide emotional relief. But what happens when markets begin recovering?
The investor now faces another difficult decision: when to reinvest.
If they wait until they feel comfortable again, they may miss part of a market recovery. If they reinvest too quickly, they may worry about another decline.
This pattern can lead to repeated attempts to time the market rather than following a strategy based on long-term financial objectives.
Other emotional investing decisions may include:
- Panic selling: Selling investments primarily because of short-term market declines.
- Loss aversion: Allowing the fear of losses to outweigh other financial considerations.
- Excessive monitoring: Constantly checking investment accounts and reacting to daily fluctuations.
- Abandoning a financial plan: Making major changes without evaluating whether personal goals or circumstances have actually changed.
These behaviors don’t mean someone is a bad investor. They illustrate how difficult it can be to separate emotional reactions from financial decisions.
Why Market Anxiety Can Feel Different in Retirement
During your working years, market declines may feel easier to tolerate because you’re still earning income and contributing to retirement accounts.
Retirement introduces a different set of considerations.
Instead of regularly adding money to investments, you may be withdrawing funds to support your lifestyle.
That can make market volatility feel more personal.
Retirees may wonder whether a decline will affect their ability to pay expenses, travel, support family members, or maintain their desired standard of living.
These concerns deserve attention because withdrawing money during market downturns can create financial challenges, particularly early in retirement.
However, responding to those concerns should begin with evaluating your retirement income strategy rather than making immediate investment changes based on fear.
How to Manage Market Anxiety Without Abandoning Your Financial Plan
Managing investment anxiety doesn’t mean ignoring market volatility or pretending that losses don’t matter.
It means recognizing when emotions may be influencing your decisions and taking time to evaluate your financial circumstances before making significant changes.
Here are four considerations that may help:
- Recognize your emotional response: Before making an investment decision, ask yourself whether something has changed in your financial situation or whether you’re reacting primarily to market movements.
- Avoid making decisions under stress: Fatigue, anxiety, and information overload can make it more difficult to evaluate financial choices objectively.
- Revisit your investment strategy: Review whether your portfolio still reflects your retirement timeline, income needs, and tolerance for risk.
- Discuss significant changes: Consider reviewing your concerns with your financial advisor before making substantial portfolio adjustments.
The goal isn’t to eliminate fear. It’s to prevent fear from becoming the primary driver of your investment decisions.
Why a Retirement Income Plan Can Help Put Market Volatility Into Perspective
For retirees, market anxiety often comes down to one important question: Will I still have enough money to support my retirement?
A retirement income plan can help address that concern by identifying potential income sources, anticipated withdrawals, and how different assets may support financial needs over time.
Depending on individual circumstances, a retirement strategy may incorporate cash reserves, bonds, diversified investments, and other income sources.
Understanding how these components work together may help retirees evaluate whether short-term market movements require changes to their financial plans.
Of course, a financial plan cannot eliminate investment losses or guarantee retirement income. Market conditions, spending needs, and personal circumstances can change.
However, having a framework for evaluating those changes may help investors avoid unnecessary emotional investing decisions.
Frequently Asked Questions About Emotional Investing
Can fear cause investors to lose money?
Yes. Fear-driven decisions, such as selling investments during a market decline and delaying reinvestment, may result in missed recoveries or realized losses. However, reducing investment risk may sometimes be appropriate depending on individual circumstances.
How can retirees manage market anxiety?
Retirees can review their income needs, investment allocation, available liquidity, and tolerance for risk. Discussing concerns with a financial advisor may also help them evaluate decisions within the context of their retirement plan.
Should I change my investments when the market drops?
Not necessarily. A market decline alone doesn’t automatically mean your investment strategy should change. Decisions should reflect your financial goals, retirement timeline, cash flow needs, and ability to tolerate investment losses.
Don’t Let Fear Make Your Retirement Decisions
Market volatility is an unavoidable part of investing, but emotional reactions don’t have to determine your financial choices.
At Nova Wealth Management, we help individuals and families in Bonita Springs, Naples, Estero, Fort Myers, and throughout Southwest Florida evaluate their investment strategies alongside retirement income planning and long-term financial goals.
As an independent Registered Investment Advisor, our focus is on providing personalized guidance that considers your individual circumstances.
Concerned about how market volatility could affect your retirement? Schedule a meeting with Nova Wealth Management to discuss your financial plan.
Source: Forbes, Mena Mirhom, M.D., October 26, 2026. Licensed through AdvisorStream.
Disclosure: This material is provided for general educational and informational purposes only and does not constitute individualized investment, tax, or legal advice. Investing involves risk, including the possible loss of principal. Diversification and financial planning do not guarantee investment results or prevent losses. Nova Wealth Management, Inc. is a Registered Investment Advisor.
“`


Sorry, the comment form is closed at this time.