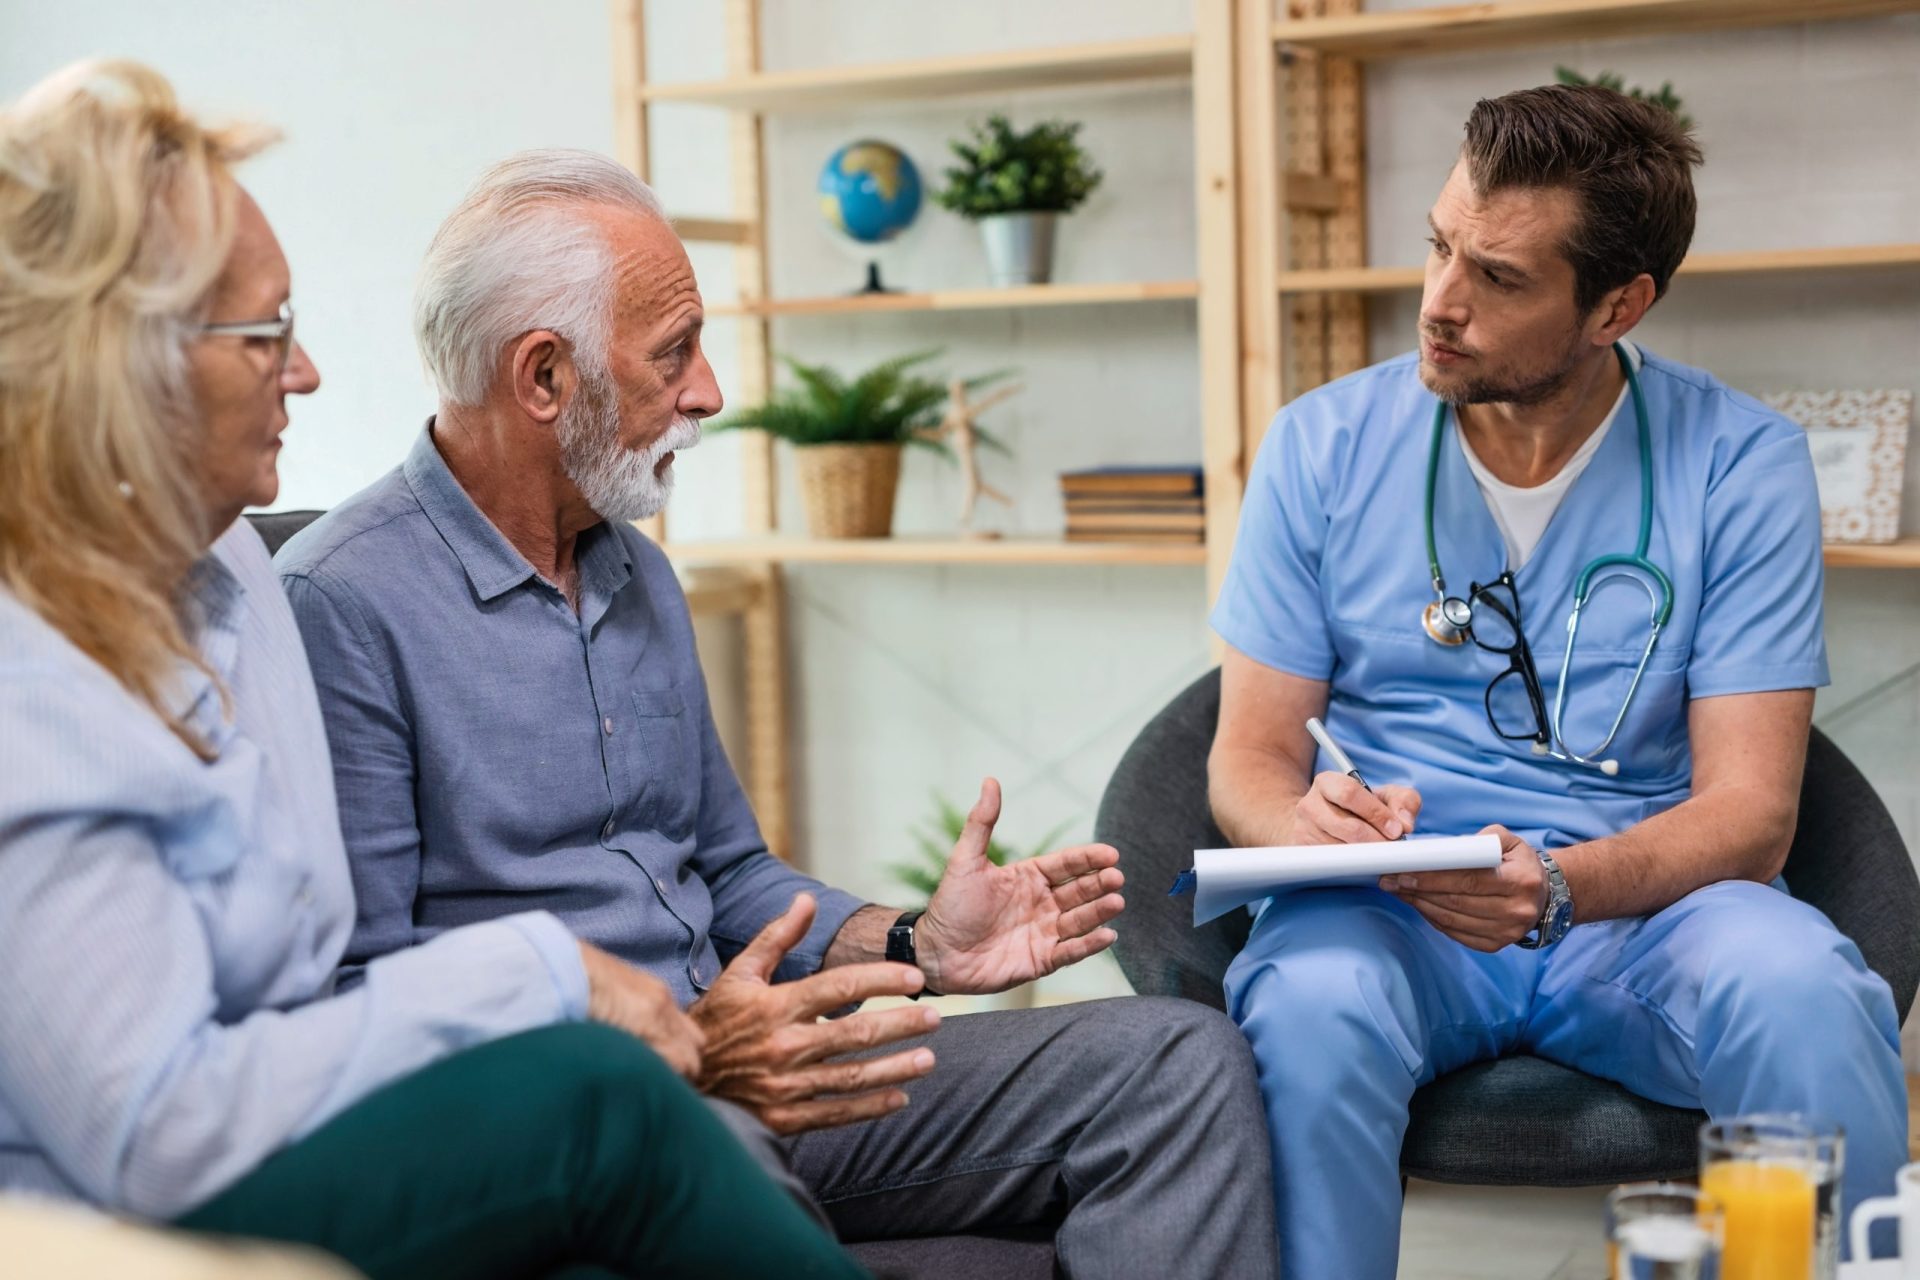
11 Mar Top Questions Clients Ask About Health Care Retirement Planning
Top Questions Clients Ask About Health Care Retirement Planning
Health care costs are one of the most important — and often misunderstood — aspects of retirement planning. While many individuals focus on income and investment strategies, health care planning can significantly influence retirement budgets and long-term financial security.
Understanding how health care fits into a retirement strategy can help individuals and families prepare more confidently for the future.
At Nova Wealth Management, based in Bonita Springs, Florida, we work with individuals and families throughout Naples, Marco Island, Estero, Fort Myers, and the surrounding Southwest Florida communities to help integrate health care planning into broader retirement strategies.
Here are some of the most common questions clients ask about health care retirement planning.
1. How Much Should I Expect to Spend on Health Care in Retirement?
Health care expenses can vary widely depending on factors such as:
-
Age at retirement
-
Overall health
-
Medicare coverage choices
-
Prescription medication needs
-
Long-term care considerations
While exact costs are difficult to predict, planning ahead helps ensure health care expenses are incorporated into retirement income strategies.
→ Learn more:
Health Care Retirement Planning
2. When Should I Enroll in Medicare?
Medicare eligibility typically begins at age 65, but enrollment timing may depend on individual circumstances.
Important considerations include:
-
Whether you are still working
-
Employer-sponsored coverage
-
Medicare enrollment windows
-
Potential penalties for late enrollment
Understanding the enrollment process can help avoid unnecessary costs or coverage gaps.
3. What Is the Difference Between Medicare Parts A, B, C, and D?
Medicare consists of multiple parts:
-
Part A – Hospital insurance
-
Part B – Medical insurance
-
Part C (Medicare Advantage) – Private plan alternatives to traditional Medicare
-
Part D – Prescription drug coverage
Evaluating these options carefully can help individuals choose coverage that fits their healthcare and financial needs.
4. How Does My Income Affect Medicare Premiums?
Many retirees are surprised to learn that income can influence Medicare premiums.
Higher income levels may trigger Income-Related Monthly Adjustment Amount (IRMAA) surcharges for:
-
Medicare Part B
-
Medicare Part D
This is why coordinating health care planning with retirement tax planning is important.
→ Related service:
Retirement Tax Planning
5. Should I Plan for Long-Term Care Costs?
Long-term care planning is often one of the most challenging retirement discussions.
Some individuals may eventually need assistance with:
-
Daily living activities
-
In-home care
-
Assisted living
-
Nursing care
Planning ahead allows families to evaluate available resources and preferences before care is needed.
6. Can My Retirement Income Cover Healthcare Costs?
Healthcare expenses must be considered within the context of overall retirement income planning.
This may include coordinating:
-
Social Security benefits
-
Pension income (if applicable)
-
Retirement account withdrawals
-
Investment income
Thoughtful planning can help ensure healthcare costs are incorporated into long-term income strategies.
→ Learn more:
Retirement Income Planning
7. How Do Healthcare Costs Change Over Time?
Healthcare expenses often increase gradually over time due to factors such as:
-
Inflation in medical costs
-
Changes in health needs
-
Prescription medications
-
Potential long-term care needs
Financial planning helps build flexibility into retirement strategies to account for these changes.
8. Should Healthcare Planning Be Part of My Financial Plan?
Yes. Healthcare planning works best when it is integrated with other financial planning areas, including:
-
Investment planning
-
Retirement income strategies
-
Tax coordination
-
Legacy planning
An integrated plan helps ensure healthcare expenses do not disrupt long-term financial goals.
→ Learn more about our comprehensive approach:
Financial Services
9. How Often Should I Review My Healthcare Plan?
Healthcare planning should be reviewed periodically, especially when:
-
Approaching Medicare eligibility
-
Experiencing health changes
-
Adjusting retirement income strategies
-
Reviewing insurance coverage options
Regular reviews help ensure decisions remain aligned with current circumstances.
10. When Should I Start Planning for Healthcare in Retirement?
Ideally, healthcare planning begins well before retirement.
Starting early allows individuals to:
-
Understand Medicare options
-
Build healthcare costs into retirement projections
-
Evaluate insurance options
-
Coordinate healthcare decisions with financial goals
Early preparation can reduce uncertainty later.
TL;DR — Health Care Retirement Planning Questions
-
Healthcare costs can vary widely in retirement
-
Medicare enrollment timing matters
-
Medicare consists of multiple coverage parts
-
Income can influence Medicare premiums
-
Long-term care planning is an important consideration
-
Healthcare costs should be integrated with retirement income planning
-
Medical costs may increase over time
-
Healthcare planning works best within a broader financial plan
Health care retirement planning helps individuals prepare for potential medical expenses while protecting long-term financial stability.
Next Steps
If you would like to better understand how health care planning fits into your retirement strategy, our team is here to help.
👉 Contact Us:
https://novawealthmanagement.com/contact-us/
📞 Phone: (239) 444-1794 (Florida) or (214) 764-9137 (Dallas)
Disclosure: This content is provided for general educational purposes only and does not constitute personalized financial, tax, or legal advice.


No Comments